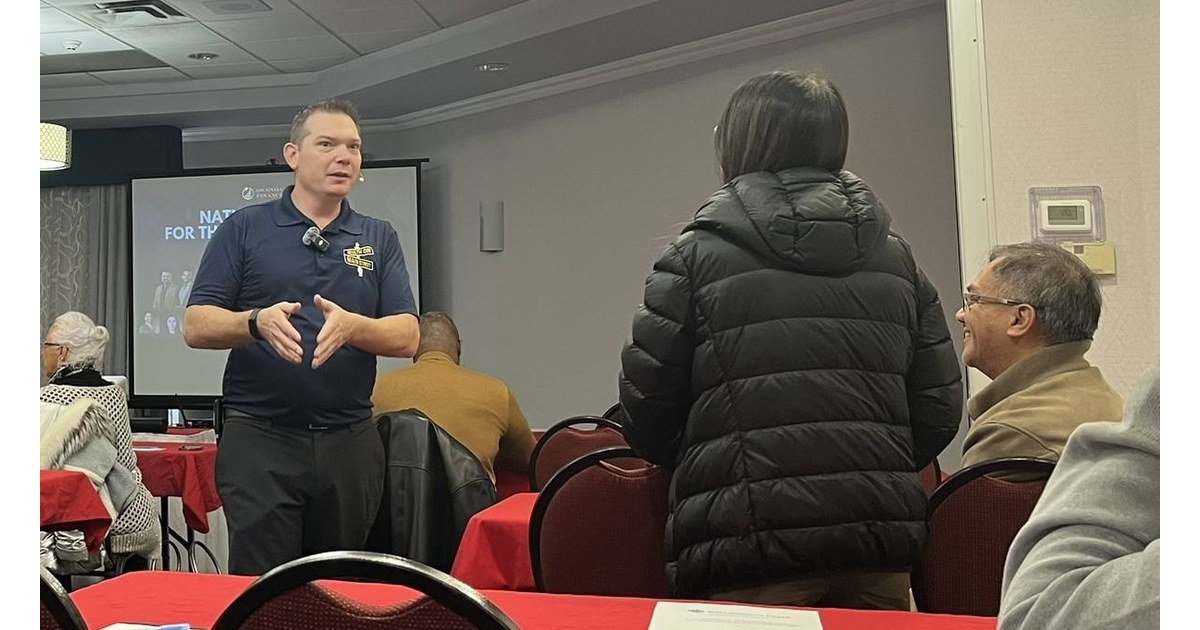
In this webinar, I take you behind the curtain of how my family uses the infinite banking concept, from our 77 whole life policies to the family constitution that guides us. I share the lessons I learned from my mentor, R. Nelson Nash, and how you can build a system that outlives you and passes on a wealth mentality, not just money.
Can you build a system that outlives you?
I start with numbers. My family system has a total death benefit of $51 million and a total cash value of $6.4 million.
It holds 77 dividend paying whole life policies on 27 lives. We pay $1.5 million in annual premium. None of it happened overnight.
My family did not come from money. I grew up around people who never let me say “I can’t.” Those two words are forbidden in my home. My kids can say “I need help,” but never “I can’t.”
My point is that anyone on this webinar can build a system that outlives them. I am living proof.
What does it take to become a good banker?
The way to become a really good banker is to be a bad one. That line came from my late mentor, R. Nelson Nash. He taught me that the infinite banking concept is more caught than taught.
He also gave me a rule. Control the banking function for your own family’s needs before you lend money to anyone outside the family. I followed it. My family paid off our principal residence 33 years ahead of schedule. That made me want to lend capital.
Of all my lending, two deals went sideways. In the first, a borrower stopped paying on a vehicle loan after about six payments. We used a civil enforcement agency to repossess it. We sold it and pursued legal remedy for the balance.
Another late mentor, Ray, told me the same thing. Be a bad banker. That is why pencils have erasers. My family tightened how we vet, underwrite and track loans. I call the mistake a gift.
Today I own policies on my wife Rebecca, my four children, and key people in my businesses. I have policies on my nieces, nephews and my sister. My family now has 16 companies valued at more than $100 million. I tie that to discovering infinite banking in July of 2008.
How does money move through the system?
I point to page 69 of Nash’s book, Becoming Your Own Banker. He compares a policy to a trust. You pay premium as the grantor. The life insurance company is the trustee. The beneficiaries are the policy owners and those who receive the death benefit.
Online sensationalism gets this wrong. Some people say all your money keeps growing inside your policy while you use the insurer’s money. That is not accurate. Once you pay premium, it is the company’s property. Property placed in a trust is no longer yours.
If it were true, how would the insurer make any money?
Cash value is not money. It is the net present value of a future death benefit. It is equity in the contract that you can borrow against on demand, on your terms.
It cannot go backward. It is not tied to the stock market, the economy or tax policy.
How should loans be repaid?
I designed my policies for premium flexibility. Out of each dollar, maybe 30 to 40 cents is the minimum required premium. The rest goes to paid up additions. On page 58, Nash says the interest paid back is really additional premium that adds to the policy’s cost basis.
My family repays more than $100,000 a month in policy loans. We treat our 77 policies as one system. Rebecca once found it frustrating to track which policy each repayment belonged to.
I told her to focus on the repayment schedule, not the policy. Build the schedule before you request the loan. Send each payment to whatever policy will hold it, and check the box.
My family charges itself 10%. Nash used that rate, and I never asked why. If the insurer charges 6% simple interest, the loan may clear sooner than the schedule. The extra payments go back into the system as premium or loan repayment.
I also invest with clear rules. If an investment does not pay me from day one, I am out. I bet on the jockey, not the horse. If I have capital in a business, I want a voice.
Why do wealthy families lose their wealth?
The biggest myth is that generational wealth is easy. About 70% of wealthy families lose their wealth by the second generation. In my experience, wealthy families do not tell their children that someday they will move out and handle their own bills. They say the family circles the wagons, and someday you will steward the family banking system.
My children have grown up with it. When they are old enough to buy their own policies, our family attorney will lay out two options.
Option A is to borrow from the family money pool at 10%. The rate is not negotiable. The repayment timeframe is. Those who choose it will be included in the family trust.
Option B is to borrow elsewhere. Then my wife and I transfer ownership of the policies on that child’s life to charities. The child is left out of the trust.
Some parents have called this harsh. I say it is a business, and I make no apologies. My oldest son took his first policy loan at age nine. My twin daughters, who are 14, are starting to borrow and repay.
We also have a one strike rule. If a borrower hides a setback and defaults, they never borrow again. If they speak up, we will work out relief. Repayments are auto debited, and defaults are at 0%.
Money fights break families apart. I saw it as a boy, when I refereed arguments between my parents.
What is a family constitution?
This is my biggest takeaway. My family’s constitution runs 55 pages printed double sided. It opens with a letter from me, along with a video. Future generations can watch me narrate it.
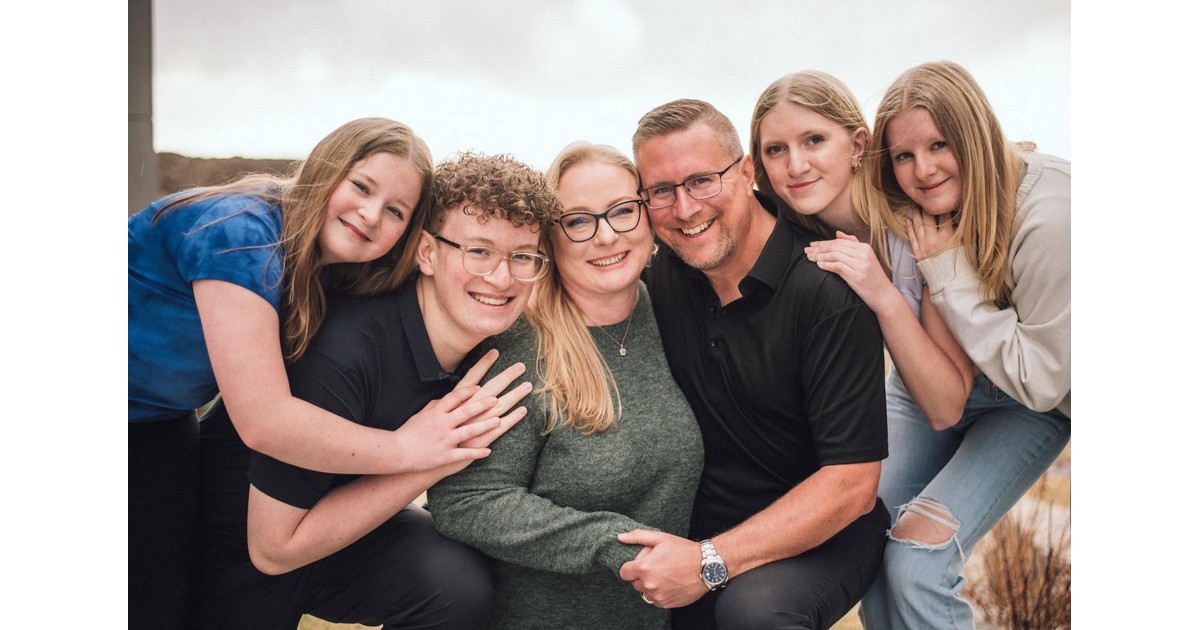
A family member reads the identity statement aloud at our annual family office meeting. Last time, my daughter Charlotte did. It covers who we are, what we believe, and our view of wealth, giving, legacy and promise.
It also sets rules. The trust cannot be collapsed. It follows the direct bloodline only. Any descendant who marries must sign a prenuptial agreement.
Trust income is supplementary. It requires gainful work and a habit of giving. Participation is never forced. Anyone may opt out with no hard feelings.
The process took a year and a half, because the trust must align with the constitution. Use professionals. I tell families not to just write their letter but to record it.
The greatest threat to wealth is not taxes. Wealthy families name a lack of shared values.
What do children learn by watching?
Rebecca and I had no playbook, since my parents had died. We set three golden rules. Be respectful, be responsible and be kind. When I raise my voice, I apologize by naming the rules I broke. Now I hear my kids do the same.
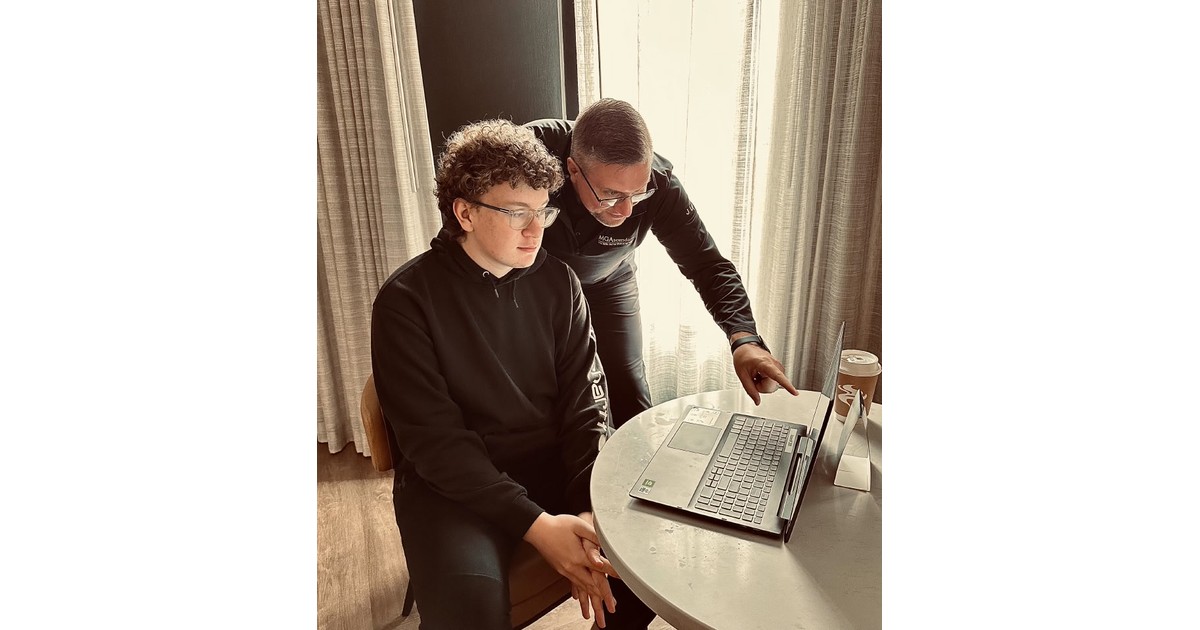
Kids listen less and watch more. If they see you build a repayment schedule and follow it, they learn the right way.
Our family meetings put values first, then a financial review. They also cover leadership development, giving, and education from Nash’s book. My family gives 15% of every gross dollar. My coaching rule is to teach, don’t tell. Families decay when money grows faster than character.
Infinite banking is ridiculously simple. Generational character is hard. Ascendant aims to coach families on transferring a wealth mentality, not only dollars.
Popular Posts
- The Infinite Banking Concept: What It Is and What It Isn’t
 Everybody’s talking about IBC. On YouTube and Facebook it gets described as a magic investment, a get-rich-quick trick, or a scheme to pay off your… Read more: The Infinite Banking Concept: What It Is and What It Isn’t
- Can Infinite Banking Make You Wealthy?It is one of the most searched questions for anyone discovering the Infinite Banking Concept forthe first time. And Jayson Lowe, who has been practicing… Read more: Can Infinite Banking Make You Wealthy?
Share This Post
Categories & Tags